Market Snapshot
Middle bar: base-year value × (1 + CAGR), rounded to two decimals. This is a calculated illustration, not a separately researched annual estimate.
The global electric motorcycle market is estimated at 989,134 units in 2025 and is projected to reach 2,158,482 units by 2030, registering a volume CAGR of 16.89% over 2026–2030. In value terms the market is estimated at USD 3.06 billion in 2025 and is projected to reach USD 6.60 billion by 2030, a CAGR of 16.62%. The market comprises new road-registered battery electric two-wheelers with motor power above 5.0 kW, covering performance scooters, maxi-scooters and electric motorcycles. India is the largest country at 46.90% of 2025 volume, and the segment's share of all electric two-wheeler sales rises from 15.91% in 2025 to 20.87% by 2030.
Market size and forecast figures are generated using Marqstats' proprietary estimation framework, updated as of October 2026.
Asia Pacific accounts for 89.54% of 2025 volume, led by India (463,930 units), China (265,309 units) and Taiwan (132,267 units). North America is the fastest-growing region at a 37.45% CAGR, and Europe is the largest market outside Asia Pacific with 33,184 units. Value grows slightly slower than volume because the average selling price eases from USD 3,094 in 2025 to USD 3,058 by 2030 as lower-priced Indian performance scooters take share.
Key Takeaways
Market Overview & Analysis
Report Summary
The global electric motorcycle market covers new battery electric two-wheelers registered for road use with motor power above 5.0 kW, the threshold that separates performance products from commuter scooters. The market is estimated at 989,134 units in 2025, up 15.03% on 859,899 units in 2024, and reaches 1,158,119 units in 2026. Volume has more than doubled from 412,680 units in 2021, and the segment's share of the global electric scooter and motorcycle market rises from 15.91% in 2025 to 20.87% by 2030. Electric bicycles, low-speed mopeds, kick scooters and electric three-wheelers sit outside the perimeter, as do internal combustion and hybrid motorcycles.
Most of the global electric motorcycle market is not made up of motorcycles. India accounts for 463,930 above-5.0 kW units in 2025, while India's dedicated electric motorcycle registrations reached 17,173 units in fiscal 2025-26, up 28% from 13,430 units. The balance consists of performance scooters such as the Ather 450 series, Ola Electric S1 Pro and Hero VIDA V1, which use peak motor ratings of 6.0 to 11.0 kW. In seven Asian markets tracked at model level, motorcycle bodies accounted for 0.05% of above-5.0 kW registrations in 2025, so the power threshold, rather than the body style, defines the market.
India is the growth engine. Its above-5.0 kW volume rises from 463,930 units in 2025 to 1,165,544 by 2030, a CAGR of 20.23%, and its share of global volume rises from 46.90% to 54.00%. Above-5.0 kW products already account for 36.21% of India's electric two-wheeler volume, against 7.57% in China, where low-power mopeds dominate. China grows at 12.63% a year to 480,826 units, and Taiwan, where above-5.0 kW products make up 73.48% of the market, grows at only 4.78% a year.
Brand-level registration data show how quickly leadership moves in India. Ather Energy Limited registered 224,424 units in 2025, up 56.63% on 143,285 units, while Ola Electric Mobility Limited fell 42.90% from 340,386 to 194,356 units after ranking first in 2024. Hero MotoCorp Limited's VIDA V1 rose 148.70% to 108,654 units, supported by the parent company's dealer network. Ola Electric began deliveries of the Roadster X electric motorcycle in May 2025 and launched an updated Roadster range from INR 79,999 in March 2026, the first attempt by a volume scooter brand to move its buyers into a motorcycle body.
India's dedicated electric motorcycle brands are small and capital-intensive. Revolt Motors expanded to 200 dealerships in April 2025 with a target of 400, Oben Electric raised INR 100 crore in a Series A round and targeted more than 150 showrooms by fiscal 2026, and Ultraviolette Automotive targeted 10,000 unit sales of the X-47 crossover in fiscal 2026. Raptee.HV prepared deliveries of India's first high-voltage electric motorcycle in November 2025. Together these brands account for a fraction of India's 17,173 electric motorcycle registrations in fiscal 2025-26, which places them in a different competitive tier from the scooter brands that supply most of India's above-5.0 kW volume.
Taiwan is a single-platform market. Gogoro Inc. models took 86.88% of tracked above-5.0 kW registrations in 2025, led by the Gogoro 3 at 29.65%, the Gogoro S1 at 20.99%, the Gogoro S2 at 15.20% and the Gogoro 2 at 14.51%. Yamaha Motor Co., Ltd.'s EC-05, built on Gogoro's battery-swap platform, added 12.59%, bringing the platform total to 99.47%. KYMCO's Ionex S6 and S7 took less than 1%, which shows that battery-swap network access, rather than motor rating, decides brand choice in Taiwan's high-power segment.
Taiwan's platform owner is under financial pressure despite its share. Gogoro Inc. guided 2025 revenue of NT$8.39 billion to NT$8.85 billion, approximately USD 270 million to USD 285 million, appointed Henry Chiang as chief executive in September 2025 and considered moving its listing from Nasdaq to Taiwan to cut costs. The company launched the entry-level Ezzy in June 2025 and forecast double-digit sales growth for 2026, and its battery-swap joint venture with Castrol Holdings extends the platform to Vietnam. Taiwan's above-5.0 kW volume grows at 4.78% a year to 167,086 units by 2030, so Gogoro's growth depends on export markets rather than its home base.
Southeast Asian volumes above 5.0 kW remain small and are led by Japanese and Vietnamese brands. Honda Motor Co., Ltd.'s CUV e: took 92.29% of tracked above-5.0 kW registrations in Indonesia in 2025, with the Yamaha E-01 at 6.71% and the Kawasaki Ninja e-1 and Z e-1 at 1.00%. In Vietnam, the Honda CUV e: registered 3,949 units and VinFast Auto Ltd.'s Theon 3,370 units, and in Thailand the CUV e: registered 313 units. Indonesia grows at 56.85% a year from 1,150 units, the fastest rate of any country, from a small base led by Japanese brands.
Europe and North America form a premium layer with distinct brands. Stark Future S.L. reported 2025 revenue of EUR 115 million, up 77%, from electric off-road motorcycles, and Acciona's Silence led Spain's electric motorcycle and light electric vehicle market in the first half of 2026. Zero Motorcycles, Inc. delivered its first X Line models to dealers in July 2025, while Harley-Davidson's LiveWire Group, Inc. reported another weak sales year in 2024. Honda unveiled its first electric motorcycle, the WN7, at EICMA in November 2025, and Royal Enfield opened European and UK bookings for the Flying Flea C6 in September 2026.
Market Dynamics
Key Drivers
Five conditions drive the electric motorcycle market, and product launches by incumbent motorcycle makers matter more than subsidy.
- Incumbent motorcycle makers enter the segment. Royal Enfield began Flying Flea C6 deliveries in Bengaluru in June 2026, Hero MotoCorp Limited confirmed its first electric motorcycle for 2027, and Bajaj Auto Limited plans electric motorcycles from fiscal 2028. Honda Motor Co., Ltd. unveiled the WN7 at EICMA in November 2025, bringing the largest internal combustion brands into the above-5.0 kW band for the first time.
- Venture capital and production capacity in India. Ultraviolette Automotive raised USD 85 million in September 2026 for a Tamil Nadu plant with initial capacity of 250,000 units a year, after a USD 45 million Series E in December 2025. Matter raised USD 25 million in August 2026 and set up capacity of 10,000 units a month in July 2025, supporting India's 20.23% growth rate.
- Lower battery costs widen the performance tier. Battery-grade lithium carbonate fell below CNY 80,000 per tonne in 2025 from more than CNY 550,000 in November 2022, which allowed brands to fit 3 to 9 kWh packs at mainstream prices. Oben Electric launched the Rorr Evo at an introductory INR 99,999 in May 2026 and Ola Electric priced the Roadster range from INR 79,999.
- Battery-swap networks remove range anxiety. Gogoro Inc.'s network supports 73.48% above-5.0 kW penetration in Taiwan, and Castrol Gogoro Mobility began battery-swap pilots with Be Group in Ho Chi Minh City in October 2026. Honda's CUV e: uses the swappable Mobile Power Pack e:, which lets buyers in Indonesia, Vietnam and Thailand avoid paying for the full battery at purchase.
- Delivery and police fleet procurement. Correos added 800 electric motorcycles to its Spanish delivery fleet in August 2025, Pos Malaysia's fleet reached 1,585 electric vehicles in September 2026, and the Royal Malaysia Police ordered 100 Jebatt F29 electric tactical motorcycles. Fleet buyers specify above-5.0 kW products for payload and highway speed.
Key Restraints
Four constraints limit the market, and the most serious are commercial rather than technical.
- Premium motorcycle brands have failed to scale. Energica Motor Company and Cake entered insolvency in 2024, and Harley-Davidson's chief executive said in February 2025 that LiveWire needs to perform after another weak sales year. Europe and North America together hold 4.05% of 2025 volume, so premium motorcycle brands sell into a pool of fewer than 41,000 units a year.
- Installed capacity runs ahead of demand. Revolt, Oben, Ultraviolette and Matter recorded rising registrations in 2026, although their installed capacity remained far above sales. India's dedicated electric motorcycle registrations of 17,173 units in fiscal 2025-26 compare with announced capacity in the hundreds of thousands, which compresses prices and margins.
- Volatile leadership in India. Ola Electric Mobility Limited lost 42.90% of its registrations in 2025, from 340,386 to 194,356 units, after service complaints rose. A brand that led the segment in one year can lose more than 140,000 units in the next, which raises the cost of capital for every new entrant.
- Rare-earth magnet supply. China's April 2025 export licensing for rare-earth elements and magnets disrupted motor supply to Indian manufacturers, and Bajaj Auto Limited cut Chetak output in August 2025. High-power motors carry more neodymium per unit than commuter hub motors, so the above-5.0 kW band is the most exposed to a repeat of the licensing delay.
Key Trends
Four shifts show where the market is moving and which companies benefit.
- Scooter brands move into motorcycle bodies. Ola Electric launched the Roadster X in 2025, Revolt Motors launched the RVX in July 2026 and Hero's VIDA registered the Ubex design in February 2026. India's electric motorcycle registrations rose 28% to 17,173 units in fiscal 2025-26, faster than the overall electric two-wheeler market.
- Battery chemistry becomes a product feature. Ola Electric's Roadster X+ with a 9.1 kWh pack built on its in-house 4680 Bharat cell received certification in December 2025, and Verge Motorcycles prepared deliveries of a solid-state battery motorcycle in January 2026. Larger packs shift the purchase decision from range to charging access and price.
- Indian brands export to Europe. Ultraviolette Automotive appointed MotoMondo to run European operations in April 2025 and entered Hungary and Central and Eastern Europe in April 2026, and TVS Motor Company Limited showed the M1-S maxi-scooter at EICMA 2025. Europe grows at 19.13% a year to 79,637 units by 2030.
- Average prices fall as volume shifts to India. The global average selling price eases from USD 3,094 in 2025 to USD 3,058 by 2030, so value grows at 16.62% against 16.89% for units. Indian performance scooters sell at approximately USD 1,210 to USD 1,580, against more than USD 8,000 for European and Japanese electric motorcycles.
Market Segmentation
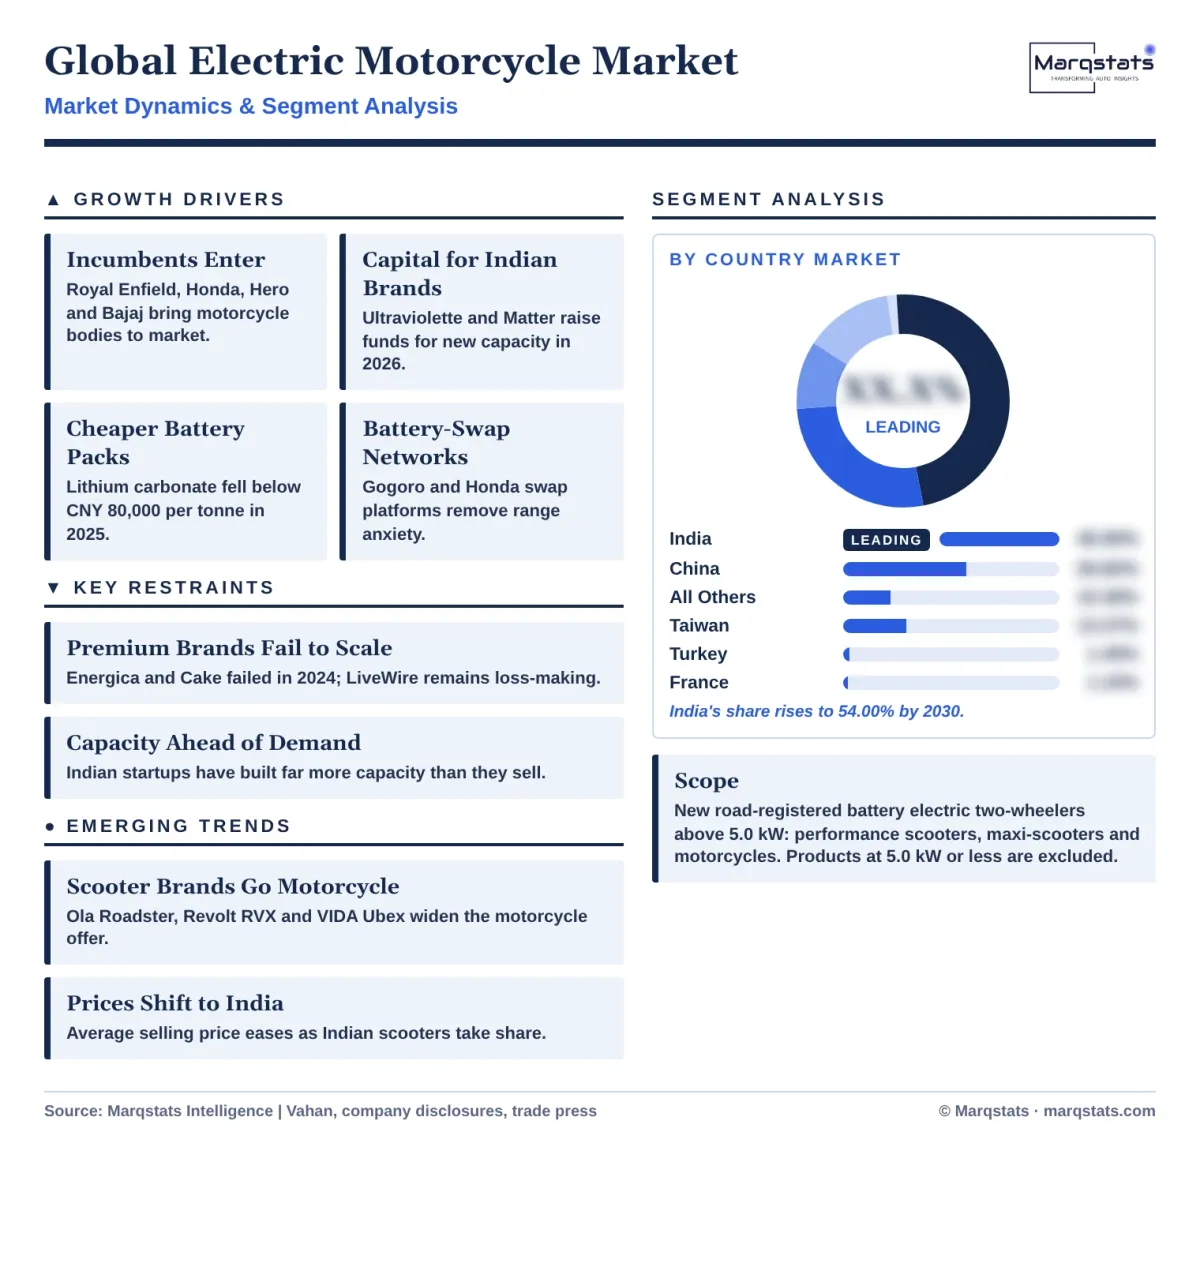
India is the largest country market and the main source of growth. It accounts for 463,930 units in 2025, 46.90% of global volume, and reaches 1,165,544 units by 2030 at a 20.23% CAGR, taking 54.00% of the market. Ather Energy Limited, Ola Electric Mobility Limited and Hero MotoCorp Limited supply most of the volume through 6.0 kW-plus performance scooters.
China is the second-largest market, although above-5.0 kW products remain a small part of its electric two-wheeler sales. It accounts for 265,309 units in 2025, 26.82% of global volume, and reaches 480,826 units by 2030 at a 12.63% CAGR, taking 22.28% of the market. Above-5.0 kW products make up 7.57% of China's registered electric moped and motorcycle volume, led by Yadea Group Holdings Ltd. and Niu Technologies.
Taiwan is the most mature market and the slowest-growing. It accounts for 132,267 units in 2025, 13.37% of global volume, and reaches 167,086 units by 2030 at a 4.78% CAGR, taking 7.74% of the market. Above-5.0 kW models make up 73.48% of Taiwan's electric two-wheeler volume, and the Gogoro platform supplies almost all of them.
Turkey is the largest market outside Asia Pacific. It accounts for 14,360 units in 2025, 1.45% of global volume, and reaches 34,773 units by 2030 at a 19.35% CAGR, taking 1.61% of the market. Yadea Group Holdings Ltd. entered the Turkish market in April 2026, and a domestic-content communique issued that month favours local assembly.
France is the largest European market. It accounts for 10,840 units in 2025, 1.10% of global volume, and reaches 23,532 units by 2030 at a 16.77% CAGR, taking 1.09% of the market. Above-5.0 kW models make up 62.99% of French electric two-wheeler volume, reflecting L3e scooters and motorcycles sold through dealers.
The remaining countries are the fastest-growing group. It accounts for 102,428 units in 2025, 10.36% of global volume, and reaches 286,721 units by 2030 at a 22.86% CAGR, taking 13.28% of the market. Mexico grows at 44.18% a year, Colombia at 36.63% and Brazil at 31.64%, as delivery fleets adopt 6 kW-class products.
By Geography
Asia Pacific
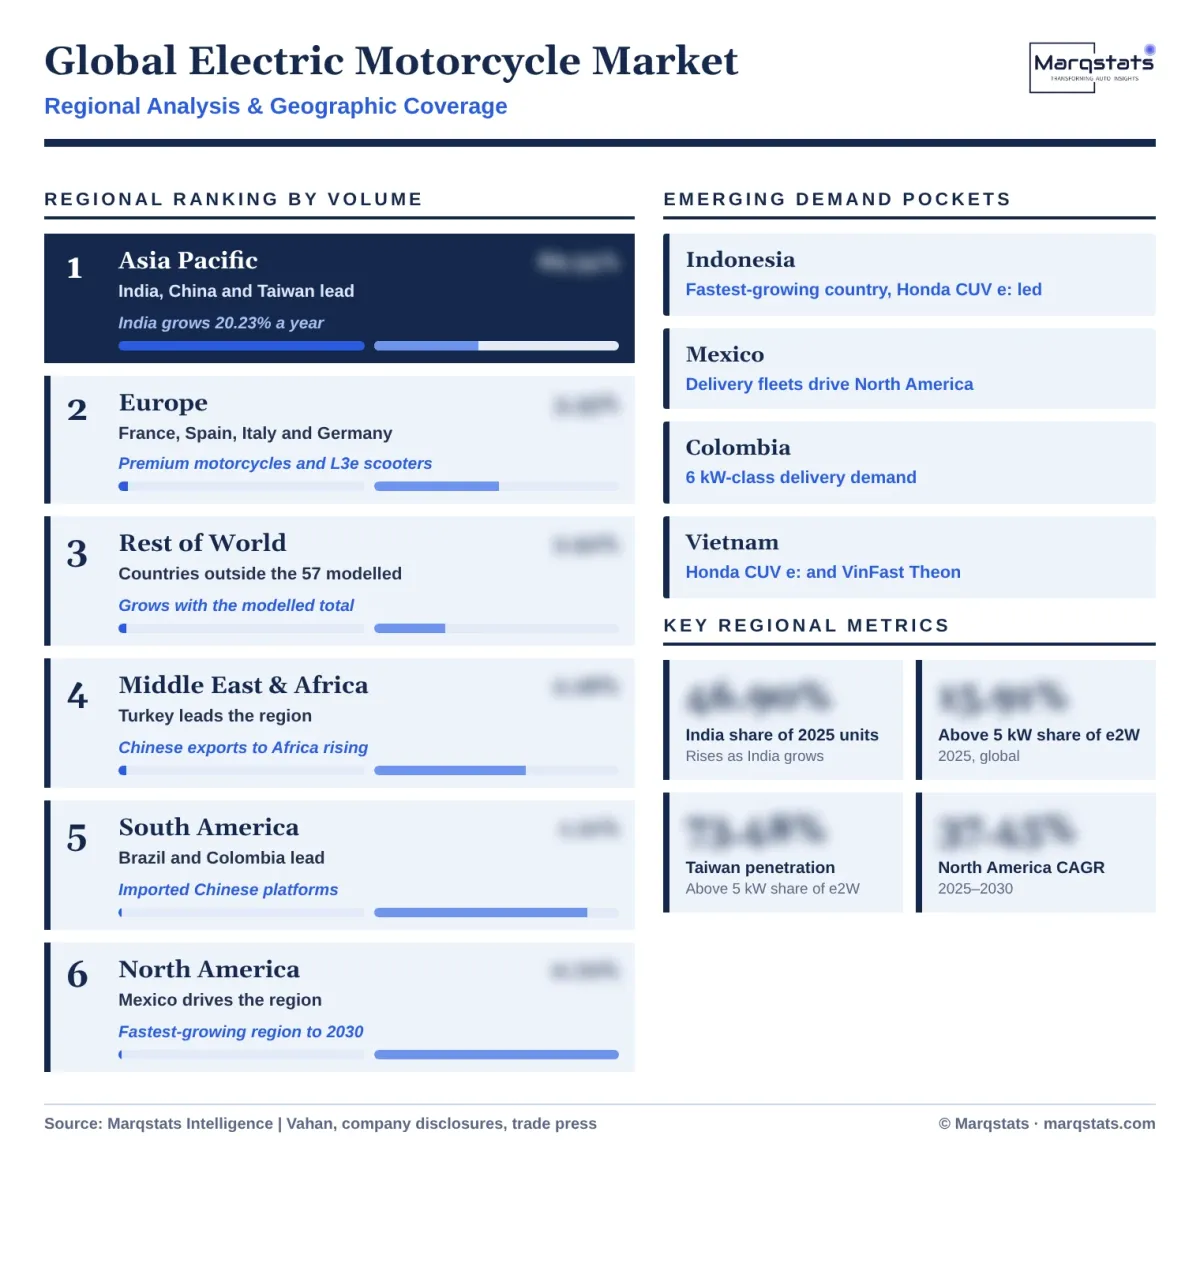
Asia Pacific is the volume centre of the global electric motorcycle market, with 885,609 units in 2025 and 89.54% of volume, easing to 87.25% by 2030 at a 16.29% CAGR. India, China and Taiwan account for most regional volume, followed by the Philippines (9,998 units) and Vietnam (9,709 units). Vietnam grows at 24.12% a year as the Honda CUV e: and VinFast Theon widen the high-power scooter offer, and Japan grows at 25.25%. China's above-5.0 kW volume of 265,309 units is led by Yadea Group Holdings Ltd. and Niu Technologies, whose performance lines compete on price with Indian scooters in export markets, and orders for Chinese electric motorcycles were booked through July 2026 on export demand from Europe, Southeast Asia and Latin America.
Europe
Europe is the largest region outside Asia Pacific, with 33,184 units in 2025 and 3.35% of volume, rising to 79,637 units by 2030 at a 19.13% CAGR. France (10,840 units), Spain (5,070 units), Italy (4,780 units) and Germany (4,370 units) lead, and above-5.0 kW products account for more than half of electric two-wheeler volume in each. Stark Future S.L., Silence, Zero Motorcycles, Inc. and Bayerische Motoren Werke AG compete with Royal Enfield and Ultraviolette Automotive, which entered the region from India.
Middle East & Africa
Middle East & Africa holds 22,558 units in 2025, 2.28% of volume, and grows at a 23.30% CAGR to 64,277 units by 2030. Turkey leads with 14,360 units, followed by Ethiopia (2,140 units), Saudi Arabia (1,416 units) and Kenya (1,157 units). Chinese exports of electric motorcycles to Africa rose sharply in the first half of 2026, and SIX-EV and BNC Motors began deploying 2,000 electric motorcycles in Africa in February 2026.
South America
South America is the second-fastest-growing region, rising from 11,966 units in 2025 to 49,176 by 2030, a 32.67% CAGR. Brazil leads with 6,940 units and grows at 31.64% a year, and Colombia grows at 36.63% from 2,480 units. Imported Chinese platforms sold by Vmoto Limited and local distributors dominate supply, and urban delivery operators account for a growing share of demand for 6 kW-class products.
North America
North America is the fastest-growing region, at a 37.45% CAGR from 6,911 units in 2025 to 33,903 by 2030, lifting its share from 0.70% to 1.57%. Mexico grows from 4,231 units to 26,364 units at 44.18% a year, while the United States holds 1,790 units and grows at 17.42%. Zero Motorcycles, Inc. and LiveWire Group, Inc. lead the United States premium segment, where unit prices above USD 12,000 limit volume.
Rest of World
Rest of World covers countries outside the 57 markets modelled individually, with 28,906 units in 2025 and 2.92% of volume. The aggregate grows at 10.71% a year to 48,079 units by 2030, and is a Marqstats estimate built from the difference between global and country-level registrations.
How Competition Is Evolving
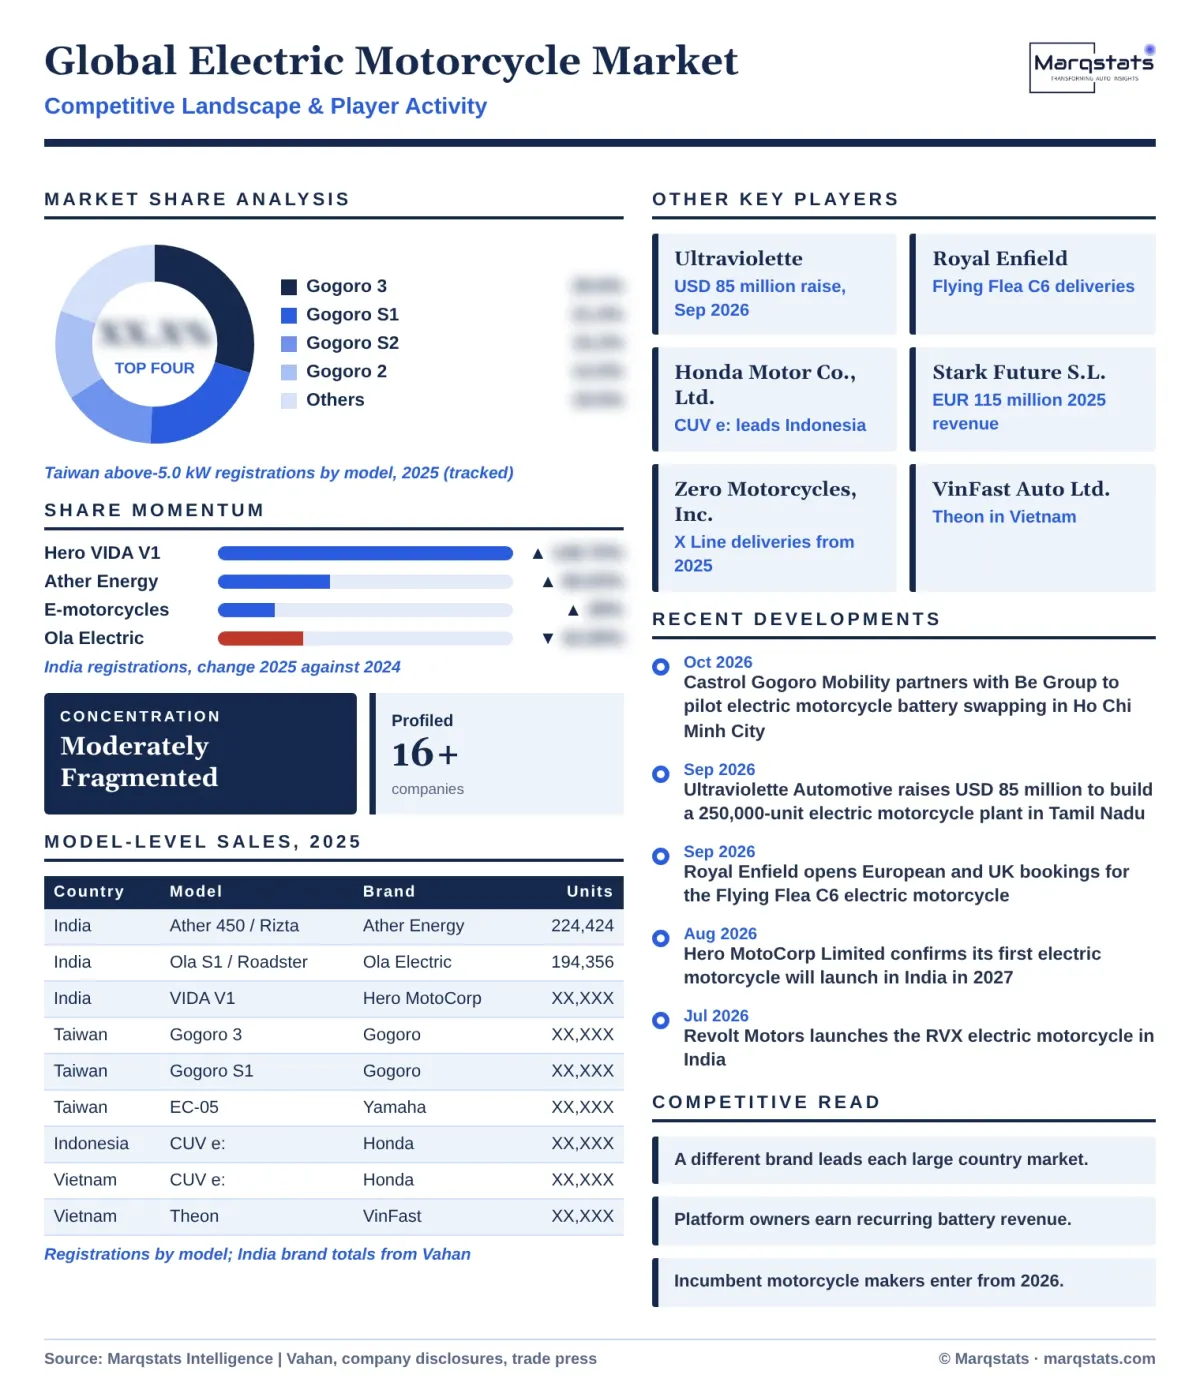
The global market is moderately fragmented, and leadership is national. In India, Ather Energy Limited, Ola Electric Mobility Limited and Hero MotoCorp Limited lead through performance scooters, and in Taiwan the Gogoro platform holds 99.47% of tracked above-5.0 kW registrations. In Indonesia, Honda Motor Co., Ltd.'s CUV e: holds 92.29%, while Europe and North America are served by specialist brands with annual volumes in the thousands. No company holds first place in more than one of the five largest national markets.
Competitive strategy splits three ways. Indian scooter brands compete on price and in-house battery technology: Ola Electric certified its 4680 Bharat cell pack in December 2025 and Ather Energy listed in India in May 2025. Platform owners such as Gogoro Inc. license their battery-swap architecture to partners including Yamaha Motor Co., Ltd., which earns recurring battery revenue. Incumbent motorcycle makers, including Royal Enfield, Honda, Hero and Bajaj, enter later with motorcycle bodies and rely on established dealer networks. Japanese brands follow the incumbent route in Southeast Asia, selling Honda's CUV e: and Yamaha's E-01 through the dealer networks that already carry their petrol motorcycles in Indonesia, Vietnam and Thailand.
The competitive question to 2030 is whether specialist electric motorcycle brands survive the arrival of incumbents. Energica and Cake failed in 2024, and LiveWire remains loss-making, while profitable specialists are those with a niche, such as Stark Future S.L. in off-road at EUR 115 million revenue. Indian specialists are raising capital ahead of the incumbents: Ultraviolette Automotive raised USD 85 million in September 2026 and Matter USD 25 million in August 2026, and Matter plans four new motorcycles before Hero's first electric motorcycle reaches showrooms in 2027.
Model concentration is high wherever data are tracked. The Gogoro 3 alone took 29.65% of tracked Taiwanese above-5.0 kW registrations in 2025, and the Honda CUV e: 53.96% in Vietnam, ahead of the VinFast Theon at 46.04%. In India, three brands supply most of the segment, and Royal Enfield's Flying Flea C6, Ultraviolette's F77 and X-47 and Ola's Roadster range are the first motorcycle-bodied products to reach volume.
Companies Covered
Companies covered in the report include:
Recent Market Activity
Table of Contents
Coverage & Segmentation
The global electric motorcycle market comprises new road-registered battery electric two-wheelers with motor power above 5.0 kW, sized in units and in USD at manufacturer selling prices. The market covers performance scooters, maxi-scooters and electric motorcycles, and is segmented by country market: India, China, Taiwan, Turkey, France and all other countries. Geographic coverage spans Asia Pacific, Europe, Middle East & Africa, South America, North America and Rest of World, with 57 countries modelled individually.
The base year is 2025, the historical period is 2021–2025 and the forecast period is 2026–2030. Electric two-wheelers rated at 5.0 kW or less, electric bicycles, kick scooters, electric three-wheelers and internal combustion motorcycles are excluded. Brand and model analysis draws on national registration series, including Vahan in India, and on company disclosures, with model-level data for India, Taiwan, Indonesia, Vietnam, Thailand and Malaysia.