Market Snapshot
Middle bar: base-year value × (1 + CAGR), rounded to two decimals. This is a calculated illustration, not a separately researched annual estimate.
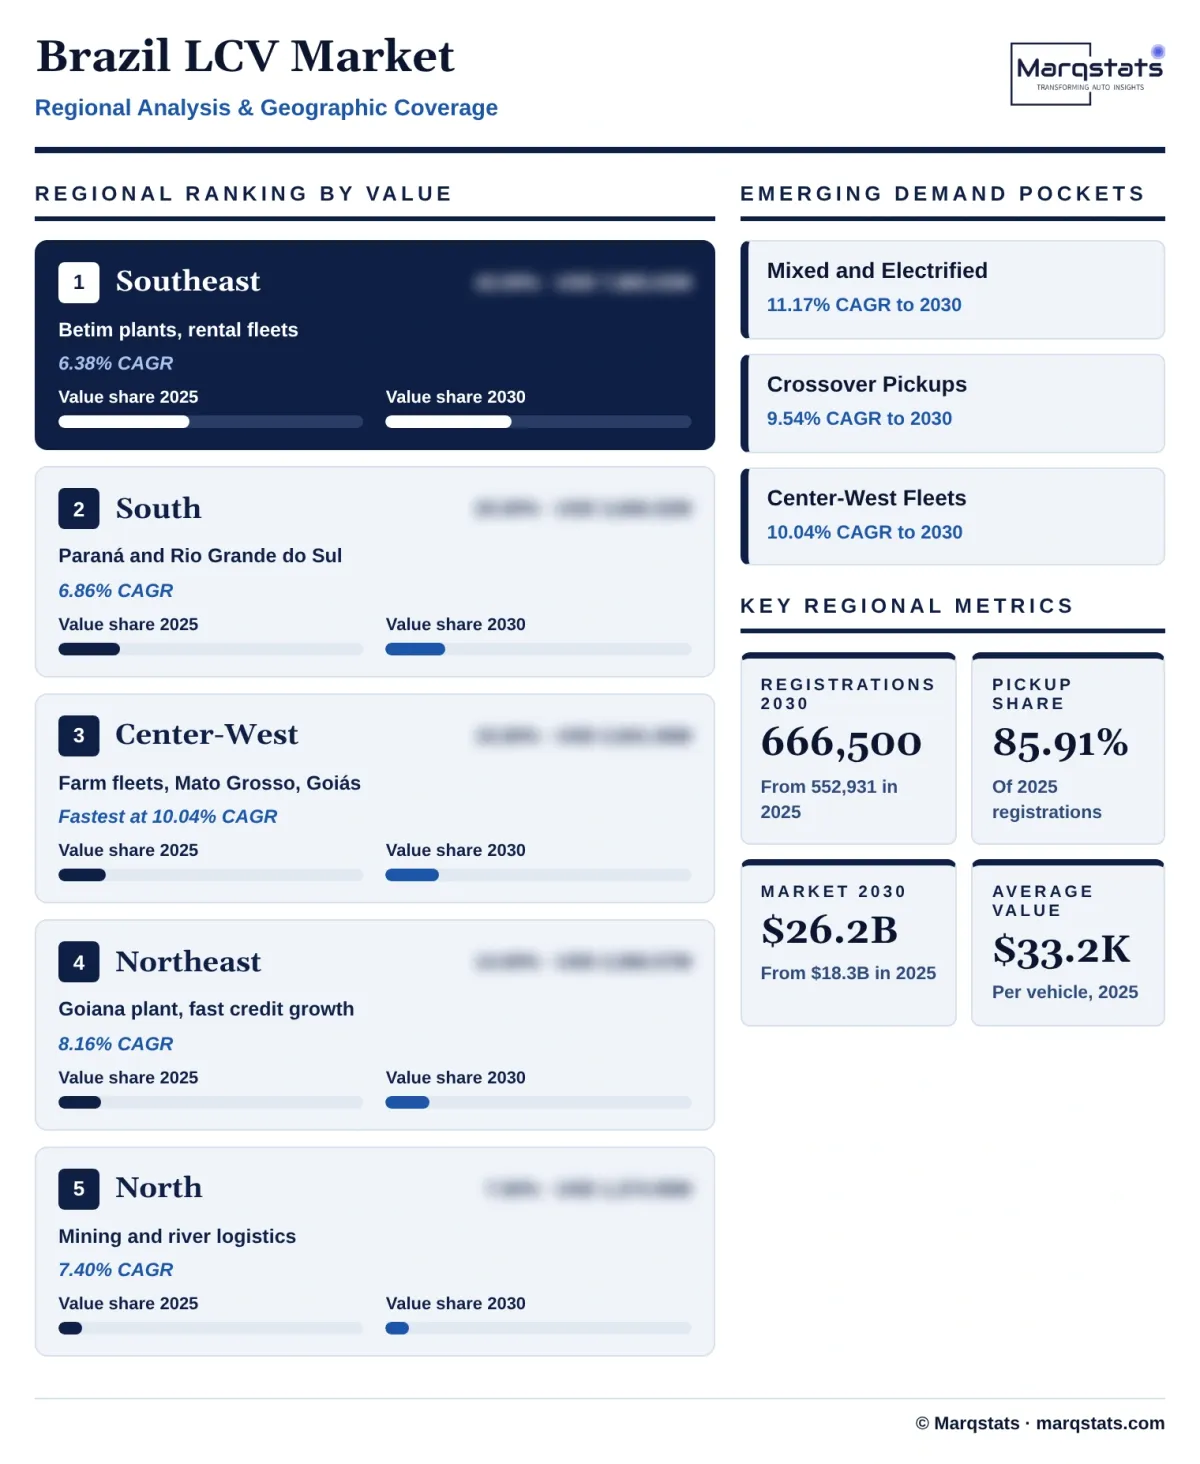
The Brazil light commercial vehicle (LCV) market size is estimated at USD 18,332.62 million in 2025 and is projected to reach USD 26,199.50 million by 2030, growing at a CAGR of 7.40% over 2026 – 2030. Registrations rise from 552,931 to 666,500 vehicles, a 3.81% annual rate, while the average transaction value per vehicle climbs from about USD 33,155 to USD 39,309 as mid-size pickups and large vans gain weight.
Marqstats defines the market as the value of new pickups and vans of up to 3.5 tonnes gross vehicle weight registered in Brazil, the class that the National Association of Motor Vehicle Manufacturers (ANFAVEA) and the National Federation of Motor Vehicle Distribution (FENABRAVE) report as comerciais leves. Value is the registered volume multiplied by a Marqstats estimate of the average transaction price, which is list price less a blended 10.00% discount, with federal and state taxes embedded, converted at BRL 5.57 per US dollar. Trucks above 3.5 tonnes, buses, passenger cars, used vehicles and exports are excluded.
Body-on-frame and full-size pickups account for 42.43% of 2025 value, diesel nameplates for 48.08% and the Southeast for 43.00%. Crossover mid-size pickups, led by the Fiat Toro and the Ram Rampage, grow fastest among the main vehicle types at 9.54% a year, and nameplates with mixed fuels or electrified drivetrains grow fastest by powertrain at 11.17%.
Key Takeaways
Market Overview & Analysis
Report Summary
Marqstats sizes the Brazil light commercial vehicle market as the value of new pickups and vans of up to 3.5 tonnes gross vehicle weight sold in the country each year. It counts compact pickups such as the Fiat Strada and Volkswagen Saveiro, crossover mid-size pickups such as the Fiat Toro and Ram Rampage, body-on-frame pickups such as the Toyota Hilux and Ford Ranger, and panel vans from the Fiat Fiorino to the Renault Master and Mercedes-Benz Sprinter. Sales of trucks above 3.5 tonnes, buses, cars and used vehicles are outside the market.
The class is large and concentrated in pickups. FENABRAVE counted 552,931 light commercial vehicles registered in 2025, up 2.91% from 537,295 in 2024, inside a year when cars and light commercial vehicles together reached 2,549,462 units and all segments, including motorcycles, reached 5,124,544. Light commercial vehicles were 21.69% of the car and light commercial total in 2025. Named pickup models account for 475,040 of the 552,931 registrations, or 85.91%.
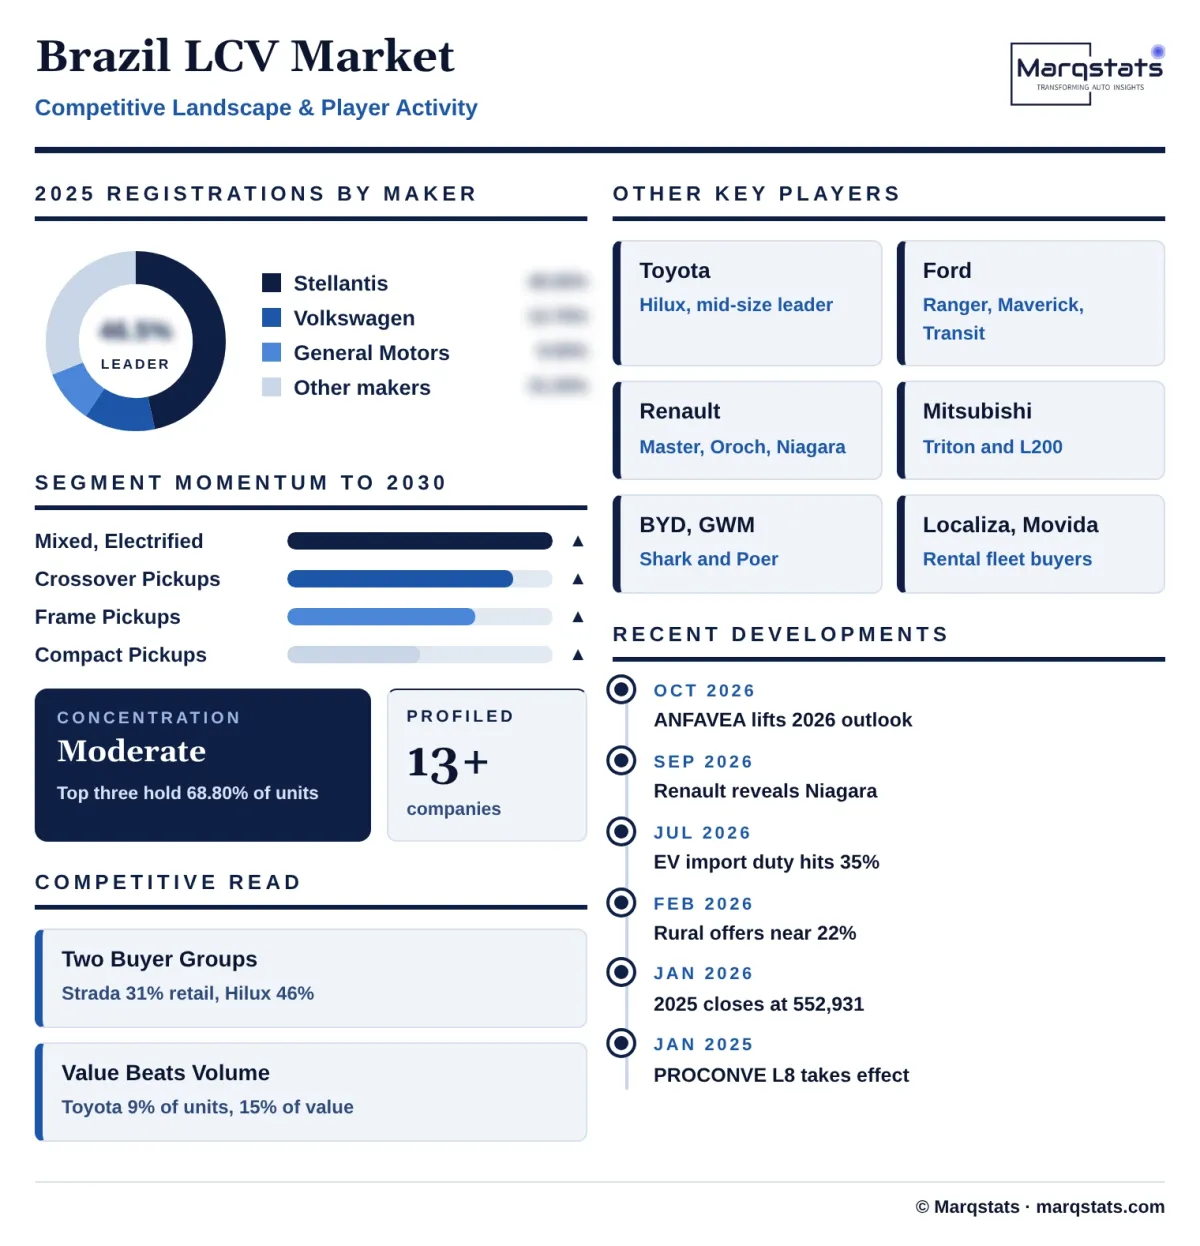
The 2026 cycle is strong in volume but weaker for commercial vehicles than for cars. The Brazilian Association of Motor Vehicle Manufacturers raised its 2026 outlook on 7 October 2026 to 3.1 million vehicles, 15.2% above 2025, with cars and light commercial vehicles together up 16.4%. FENABRAVE data show the light commercial segment at 428,109 registrations from January to September 2026, up 8.02%, against cars at 1,728,390, up 22.49%. The light commercial share of the car and light commercial total therefore fell from 21.69% in 2025 to 19.85% in the first nine months of 2026.
Policy changes the mix more than the total. The eighth phase of the national vehicle emissions programme (PROCONVE L8) took effect on 1 January 2025 under CONAMA Resolution 492/2018, with corporate averages of 50 mg/km of NMOG plus NOx in 2025, 40 in 2027 and 30 in 2029. The Green Mobility and Innovation programme (MOVER, Law 14.902/2024) offers R$ 19.3 billion in financial credits between 2024 and 2028, and the import duty on electric vehicles rises to 35% in July 2026, which favours vehicles built in Brazil and Argentina over Chinese imports.
Marqstats estimates the market at about BRL 102.11 billion in 2025, equal to USD 18,332.62 million at the 2025 average of BRL 5.57 per US dollar, and a registered volume of 552,931 vehicles at an average transaction price of about BRL 184,675.
Brazil Light Commercial Vehicle (LCV) Market Size and Forecast
The Brazil light commercial vehicle market grows from USD 18,332.62 million in 2025 to USD 26,199.50 million in 2030, a CAGR of 7.40%. Volume supplies roughly half of the growth: registrations rise at 3.81% a year, from 552,931 to 666,500 vehicles, and the average transaction value rises at 3.46% a year, from about USD 33,155 to USD 39,309, because prices rise 3.00% a year in reais at constant exchange rates and the mix moves to mid-size pickups and large vans.
The 2025 value is built bottom-up from model-level registrations and prices. Marqstats applies FENABRAVE registrations for 28 named nameplates, from the Fiat Strada at 142,903 to the GWM Poer at 758, and treats the 20,527 remaining vehicles as other light commercials at an average of about BRL 207,000. Each nameplate is priced at a volume-weighted list price built on 2026 entry prices and version ladders, such as the Strada at R$ 113,490, the Toro at R$ 159,490 to R$ 228,490 and the Hilux at R$ 282,390 for the simplest double cab, and a blended 10.00% discount is applied for fleet bonuses and dealer offers. Offers on single versions reached about 22% in February 2026, so 10.00% is a market average and not a ceiling.
The 2026 estimate is 595,000 vehicles, a 7.61% rise on 2025, because FENABRAVE reported 428,109 registrations from January to September, up 8.02%, and the last quarter is the seasonally strongest. Marqstats expects growth to slow to about 2.88% a year from 2027 to 2030, as the rental fleet renewal that lifted 2026 is followed by normal replacement cycles and as interest costs weigh on private buyers.
Electrified and full-size pickups add value faster than volume. Marqstats expects the group, which includes the BYD Shark, the GWM Poer and the Ford F-150, Ram 1500 and Chevrolet Silverado, to rise from 5,245 vehicles in 2025 to 14,000 in 2030, equal to 2.10% of registrations and 4.59% of value. The BYD Shark, at 1,133 registrations in 2025 and 373 in 2026 to July, shows that the group depends on import duties and prices, so the forecast is a Marqstats estimate that assumes local assembly of Chinese plug-in pickups.
Marqstats tracks four indicators to monitor the forecast: monthly FENABRAVE registrations of light commercial vehicles by model, the pace of the import duty on electrified vehicles after July 2026, fleet purchases by rental companies such as Localiza&Co and Movida, and the launch calendar of mid-size pickups, including the Renault Niagara and the Volkswagen Tukan.
Market Dynamics
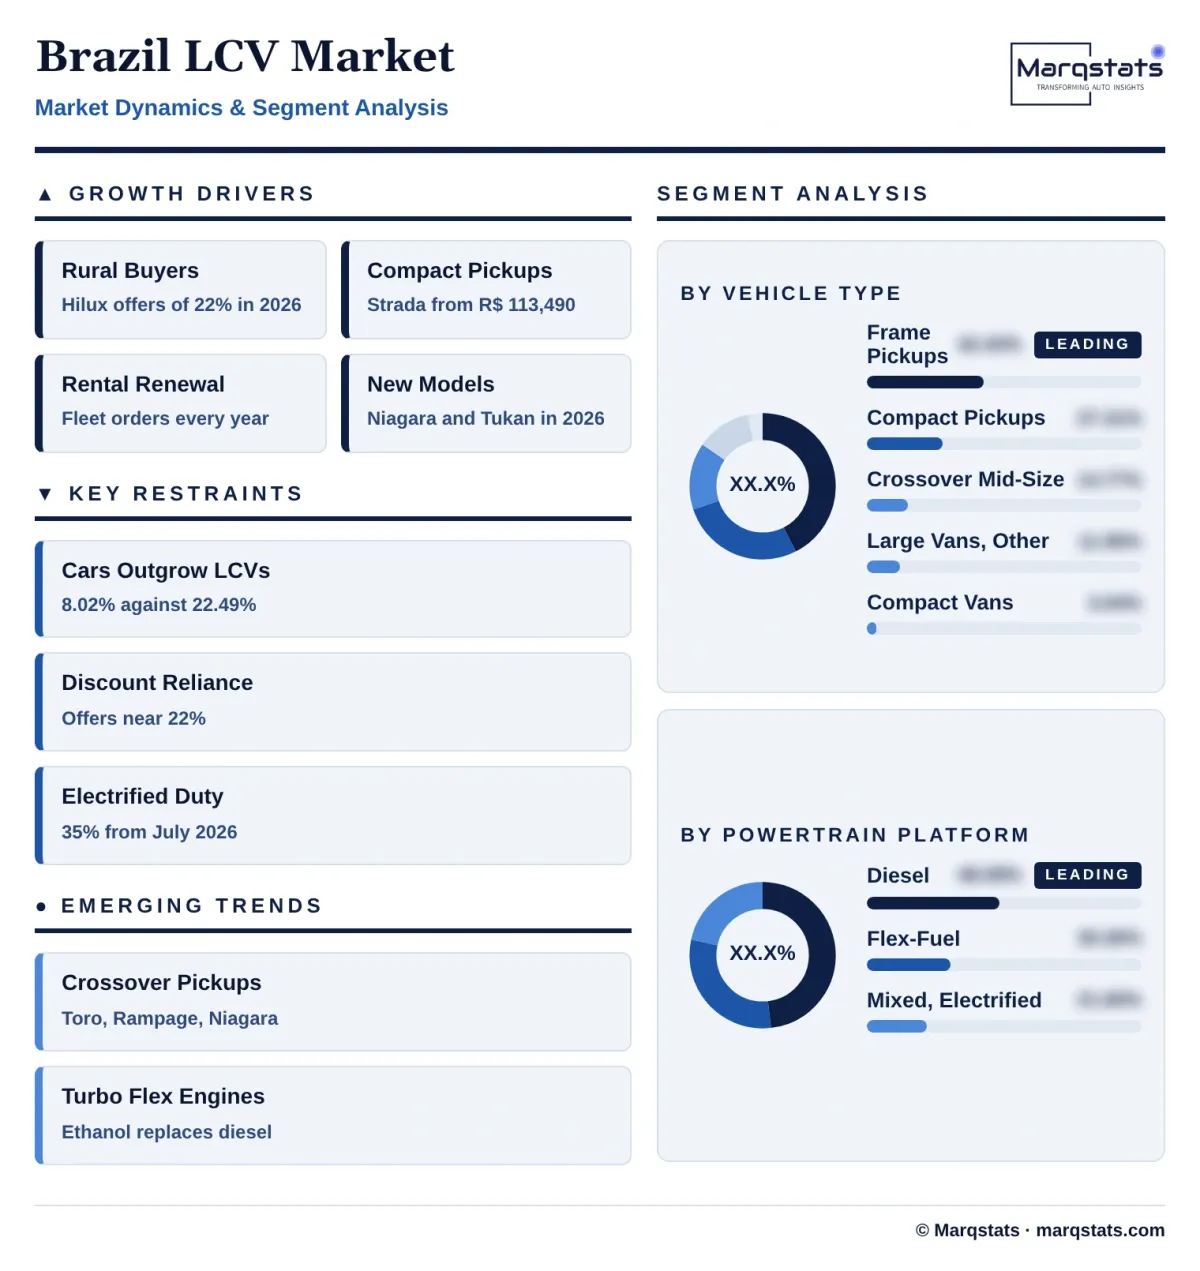
Key Drivers
Six forces keep demand for light commercial vehicles above half a million units a year in Brazil.
- Farm and rural buyers pay for capability. Toyota offered the Hilux double cab at R$ 220,264 against a list price of R$ 282,390 to rural producers and small fleets in February 2026, a discount of about 22%, and mid-size four-wheel-drive pickups such as the Hilux, Ranger and S10 registered 125,654 units in 2025 across just four models. Crop and livestock income in the Center-West and South keeps this demand steady.
- Compact pickups give small businesses a low entry cost. The Fiat Strada starts at R$ 113,490, the Volkswagen Saveiro at R$ 112,690 and the Chevrolet Montana at R$ 131,990, and the Strada alone registered 142,903 units in 2025, 25.84% of all light commercial vehicles. A pickup at that price replaces a hatchback and a small truck for tradespeople, couriers and farms.
- Fleet renewal by rental companies adds volume. Associação Brasileira das Locadoras de Automóveis (Abla) data for 2022 counted 1,136,517 cars and commercial vehicles owned by rental companies, and Localiza&Co and Movida resell vehicles after short cycles, so renewal creates a steady annual order of Strada, Saveiro and Fiorino units that retail demand alone would not provide.
- Credit remains available. Brazilians financed 7.3 million vehicles in 2025, up 2% and the best result since 2011, including 2.6 million new vehicles, and the Northeast and North recorded the fastest growth in financed vehicles at 12.3% and 9.8%. Instalment finance is how most individual buyers reach the R$ 235,000 to R$ 335,000 entry prices of mid-size pickups.
- New models widen choice. Renault revealed the Niagara in September 2026 for Brazilian dealers in November, built at Santa Isabel in Cordoba with a stated capacity of 40,000 to 60,000 vehicles a year, the Volkswagen Tukan was revealed without camouflage, the Fiat Titano registered 6,437 units in 2025, and the Toro was renewed for 2026, so every mid-size price band has a new entrant.
- The 2026 cycle lifts the whole market. The Brazilian Association of Motor Vehicle Manufacturers (ANFAVEA) forecasts 2026 cars and light commercial vehicles up 16.4%, and light commercial registrations in January to September 2026 reached 428,109, up 8.02%, with September at 52,355 units.
Key Restraints
Four constraints slow the market even in a record year for total vehicle sales.
- Light commercial vehicles are growing slower than cars. Registrations rose 8.02% from January to September 2026 against 22.49% for cars, and the light commercial share of the combined total fell from 21.69% to 19.85%, as buyers who once chose a double-cab pickup for family and work now have Chinese electrified cars and sport utility vehicles at similar prices.
- Mid-size pickups depend on discounts. The Hilux list price of R$ 282,390 and the Ranger entry price of R$ 259,000 sit well above the R$ 113,490 of a Strada, and the 22% offers seen in February 2026 show that factories use price cuts to move volume, which holds back realised value per vehicle.
- Electrified pickups face import duty and thin demand. The import duty on electric vehicles rises from 25% to 35% in July 2026, the BYD Shark launched at R$ 379,800 in October 2024 and sold at R$ 344,990 by July 2026, its FIPE resale value fell R$ 102,000 or 27%, and only 373 units were registered in 2026 to July against 1,133 in 2025.
- Emission rules raise engine cost. PROCONVE L8 limits corporate averages to 50 mg/km of NMOG plus NOx in 2025, 40 in 2027 and 30 in 2029, so manufacturers retune engines, as the 1.3 turbo flex engine in the Jeep Renegade, Compass and Commander fell from 185 hp to 176 hp, and the same corporate average binds the pickups and vans of each maker, which passes part of the cost to buyers.
Key Trends
Four shifts are changing which pickups and vans Brazilian buyers choose.
- Crossover mid-size pickups multiply. The Fiat Toro and Ram Rampage registered 52,133 and 26,140 units in 2025, the Ford Maverick 4,061, and the Renault Niagara and Volkswagen Tukan join in late 2026, creating a unibody class between the Strada and the Hilux with a 1.3 turbo flex engine as its common choice.
- Turbo flex engines replace diesel in lighter pickups. The Toro, Montana and Niagara use 1.3 or 1.2 turbo flex engines that run on ethanol, while the Hilux, Ranger, S10, Triton, Titano, Frontier, L200 and Amarok remain diesel-only nameplates with 144,797 units in 2025.
- Direct-sale offers set prices. Fiat offered the Strada Freedom Cabine Plus at R$ 94,584 against a list of R$ 120,490 to direct buyers in February 2026, Volkswagen offered the Saveiro at R$ 87,899 against R$ 112,690, and the Fiorino was offered to company buyers at under R$ 108,000 against R$ 127,000.
- Chinese brands enter through plug-in and diesel pickups. The BYD Shark, the GWM Poer and the Leapmotor production planned by Stellantis at Goiana show that Chinese makers seek local assembly to avoid the 35% duty, although volumes are below 2,000 vehicles in 2025.
Strategic Implications
- For pickup makers, the market rewards a presence in both halves. The Strada, Montana and Saveiro sell 76.06% of their volume to non-retail buyers, while the Hilux, Ranger, Triton and S10 sell 48.21% to individuals, so a maker needs a fleet offer for the first group and a dealer and finance offer for the second, and cannot treat them as one customer.
- For new entrants with Chinese or imported platforms, the 35% duty on electrified imports from July 2026 makes local assembly or kits the practical route. The Renault Niagara is built in Argentina, Stellantis plans Leapmotor output at Goiana, and an entrant that depends on fully built imports faces price cuts like the R$ 34,810 reduction on the BYD Shark within 21 months.
- For van makers and fleet buyers, the Fiorino at 21,329 and the Master at 15,763 show that company buyers lead the van segment. Offers to company buyers of about R$ 19,000 on the Fiorino make direct fleet contracts with delivery companies and rental groups the main route, and retail dealers matter little.
- For finance and leasing companies, the gap between R$ 113,490 and R$ 282,390 entry prices splits the book in two. Small-ticket loans and leasing on compact pickups suit micro-businesses, and larger loans with rural income evidence suit mid-size pickups, where residual values hold better than electrified models.
- For parts and service providers, a diesel-only mid-size fleet of 144,797 units registered in 2025 and a Strada fleet growing by 142,903 a year define the aftermarket. Diesel emission systems under PROCONVE L8 and turbo flex engines need different parts, training and workshops.
Market Segmentation
Compact pickups account for 27.31% of 2025 value, USD 5,007.47 million, and 43.88% of units, with 242,664 registrations. The Fiat Strada leads at 142,903 units, followed by the Volkswagen Saveiro at 67,753, the Chevrolet Montana at 20,384 and the Renault Oroch at 11,624. The segment grows at 5.61% a year to USD 6,578.57 million as units rise to 275,000, which is the slowest rate of the pickup groups because buyers trade up to crossover models.
Crossover mid-size pickups account for 14.77% of 2025 value, USD 2,708.54 million, and grow fastest among the large vehicle types, at 9.54% a year, to USD 4,271.31 million and 16.30% of the market. They include the Fiat Toro at 52,133 units, the Ram Rampage at 26,140 and the Ford Maverick at 4,061, and the Renault Niagara and Volkswagen Tukan add choice in 2026 and 2027.
Body-on-frame and full-size pickups account for 42.43% of 2025 value, USD 7,775.75 million, and are the largest segment by value although they hold 27.14% of units. The Toyota Hilux registered 49,732 units, the Ford Ranger 34,063 and the Chevrolet S10 31,458, with the Mitsubishi Triton, Fiat Titano, Nissan Frontier, Mitsubishi L200 and Volkswagen Amarok below them. The segment grows at 7.90% a year to USD 11,374.37 million.
Compact and mid vans account for 3.54% of 2025 value, USD 649.59 million, with 29,411 registrations led by the Fiat Fiorino at 21,329, the Renault Kangoo at 4,482 and the Fiat Scudo at 3,600. They grow at 6.03% a year to USD 870.56 million, driven by last-mile delivery and trades, and are bought almost entirely by companies.
Large vans and other light commercials account for 11.95% of 2025 value, USD 2,191.27 million, and grow at 7.22% a year to USD 3,104.69 million. The Renault Master leads at 15,763 registrations, followed by the Mercedes-Benz Sprinter 417 at 3,757, the Fiat Ducato at 3,361, the Ford Transit at 2,636 and the Sprinter 517 at 2,436, and 20,527 other vehicles complete the group.
Nameplates sold only with flex-fuel petrol and ethanol engines account for 30.26% of 2025 value, USD 5,546.54 million, and 48.56% of units, or 268,475 registrations. They are the Strada, Saveiro, Montana, Oroch, Fiorino and Kangoo, and they grow at 5.65% a year to USD 7,301.01 million. Marqstats classifies by the fuel offer of each nameplate, which the manufacturer range sets.
Nameplates sold only with diesel engines account for 48.08% of 2025 value, USD 8,815.95 million, and 31.24% of units, or 172,750 registrations. They include the Hilux, Ranger, S10, Triton, Titano, Frontier, L200, Amarok, Master, Sprinter, Ducato and Transit, and they are the largest group by value. They grow at 6.64% a year to USD 12,157.64 million.
Nameplates that offer several fuels, plug-in hybrids and electrified drivetrains, together with other light commercials, account for 21.66% of 2025 value, USD 3,970.13 million, and 111,706 registrations. The group includes the Toro, Rampage, Maverick, Scudo, Shark and full-size pickups, and grows fastest, at 11.17% a year, to USD 6,740.85 million and 25.73% of the market.
By Geography
Southeast
The Southeast accounts for 43.00% of 2025 value, USD 7,883.02 million, and grows at 6.38% a year to USD 10,741.80 million. It holds the factories at Betim in Minas Gerais and the São Paulo market, and it is overstated in registrations because rental companies register fleets there: Abla data for 2022 put 68.8% of 1,136,517 rental-company vehicles in Minas Gerais and 11.5% in São Paulo, where the annual vehicle tax is 1% for rental companies. Marqstats allocates value by registration, as buyers and lenders do.
South
The South accounts for 20.00% of 2025 value, USD 3,666.52 million, and grows at 6.86% a year to USD 5,108.90 million. Paraná and Rio Grande do Sul combine soybean, wheat and livestock income with a dense network of dealers, and the region buys more Hilux and Ranger double cabs than its share of population suggests.
Center-West
The Center-West accounts for 15.50% of 2025 value, USD 2,841.56 million, and grows fastest among regions, at 10.04% a year, to USD 4,584.91 million and 17.50% by 2030. Mato Grosso, Mato Grosso do Sul and Goiás run farm fleets that use pickups on unpaved roads, and the region's share of value is higher than its share of units because buyers choose mid-size diesel models.
Northeast
The Northeast accounts for 14.00% of 2025 value, USD 2,566.57 million, and grows at 8.16% a year to USD 3,798.93 million. Financed vehicles in the region grew 12.3% in 2025, the fastest of any region, and Stellantis builds the Toro and Rampage at Goiana in Pernambuco, which keeps supply local.
North
The North accounts for 7.50% of 2025 value, USD 1,374.95 million, and grows at 7.40% a year to USD 1,964.96 million. Financed vehicles grew 9.8% in 2025, and mining, river logistics and infrastructure works buy diesel pickups and vans, although long distances and thin dealer networks cap volume.
How Competition Is Evolving
The market is moderately concentrated and led by Stellantis. Marqstats counts registrations of named nameplates from FENABRAVE: Stellantis, with the Fiat Strada, Toro, Fiorino, Titano, Scudo and Ducato and the Ram Rampage and 1500, registered 257,093 vehicles in 2025, 46.50% of the market and 35.80% of value. Volkswagen follows with 70,487 (12.75%) and General Motors with 52,798 (9.55%), so the top three hold 68.80% of units.
Value shares differ from unit shares because mid-size pickups are costly. Toyota, with only the Hilux at 49,732 units, holds 8.99% of units but 14.90% of value, and Ford, with the Ranger, Maverick, F-150 and Transit at 41,968 units, holds 7.59% of units and 12.07% of value. Volkswagen, which relies on the Saveiro, holds 8.08% of value.
Stellantis defends its lead from the factory. The company stated on 2 January 2026 that it registered more than 750,000 vehicles in Brazil in 2025, about 29.3% of total sales, that the Strada was Brazil's best seller for the fifth consecutive year, and that the Toro ranked first and the Rampage second among compact pickups. It plans Leapmotor production and four Bio-Hybrid models at Goiana. Renault, Mercedes-Benz, Mitsubishi and Nissan hold 10.56% of units, and BYD and GWM hold 0.34%.
Competition is moving from price to platform. The Renault Niagara, built in Argentina, and the Volkswagen Tukan enter the Toro class in late 2026, rental groups such as Localiza&Co and Movida buy through direct contracts, and Chinese entrants face a 35% duty on electrified imports. Unnamed vehicles complete the market at 20,527 units, 3.71%.
Companies Covered
Companies covered in the report include:
Recent Market Activity
Table of Contents
Coverage & Segmentation
The study covers the Brazil light commercial vehicle market, with 2025 as the base year and 2026 – 2030 as the forecast period. It covers new pickups and vans of up to 3.5 tonnes gross vehicle weight registered in Brazil, as classified by FENABRAVE and ANFAVEA as light commercial vehicles, segmented by vehicle type, powertrain platform and region. Values are Marqstats estimates of the transaction value in US dollars at BRL 5.57 per US dollar, the 2025 average, with federal and state taxes embedded and a blended 10.00% discount applied to list prices.
Trucks above 3.5 tonnes, buses, passenger cars including sport utility vehicles, used vehicles, exports and conversions are excluded. Segment and regional splits, nameplate prices and the forecast are Marqstats estimates built on FENABRAVE and ANFAVEA registrations, model rankings and dealer list prices. Live Marqstats reports on the Brazil Electric Truck market, Brazil Electric Vehicle market and Brazil Used Car market are adjacent, and their figures should not be added to this market.
