A Channel Growing Fast Enough to Notice
Retail channel shifts in lubricants markets usually move slowly, a percentage point or two a year. Thailand's organized fast-fit segment is not moving slowly. Three national chains are expanding branch counts fast enough that the independent garage's share of the market is under direct, visible pressure within a single forecast window, not a decade-long trend.
The Numbers Behind the Expansion
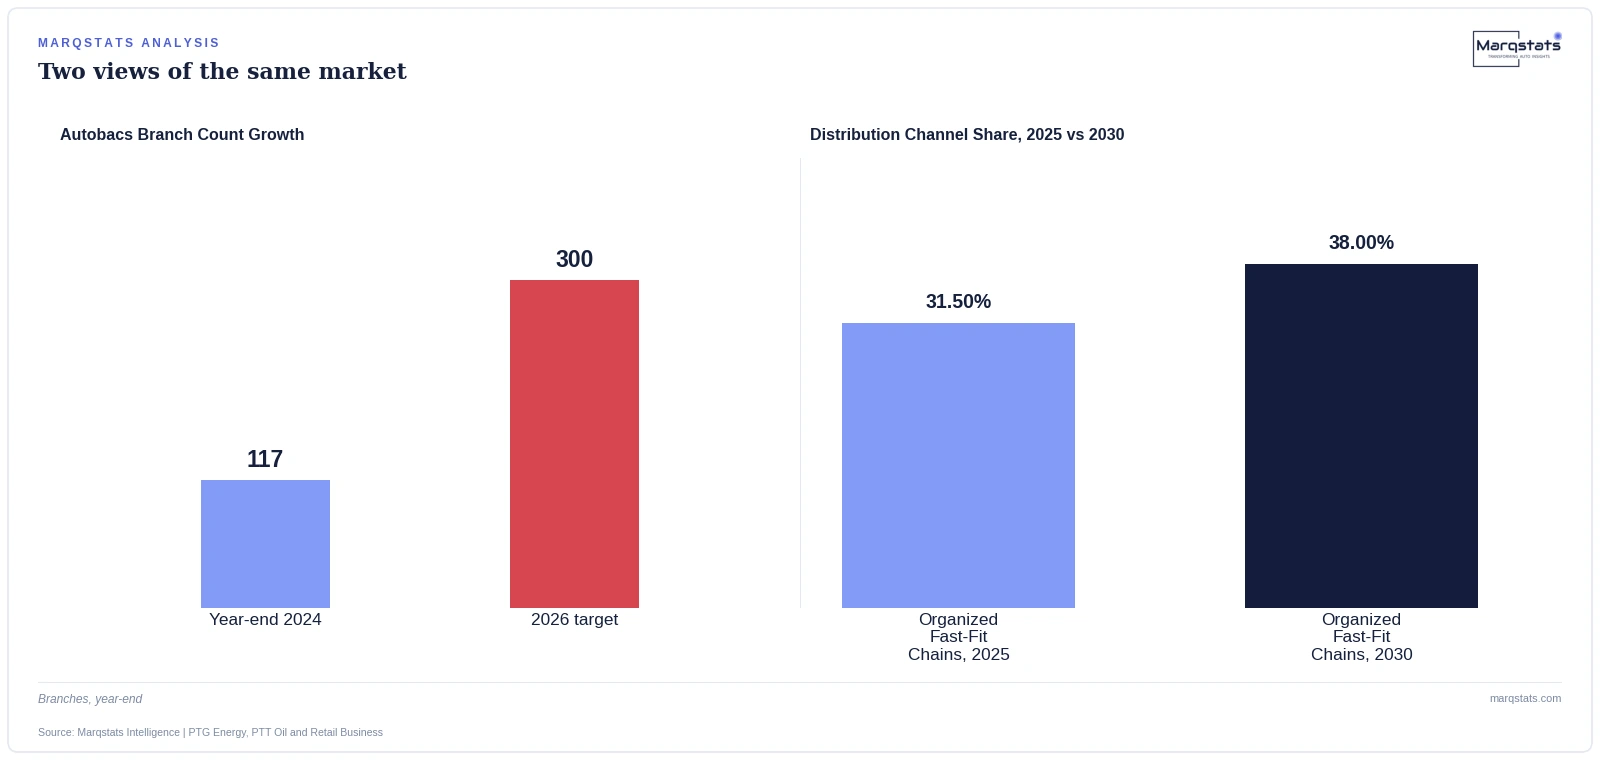
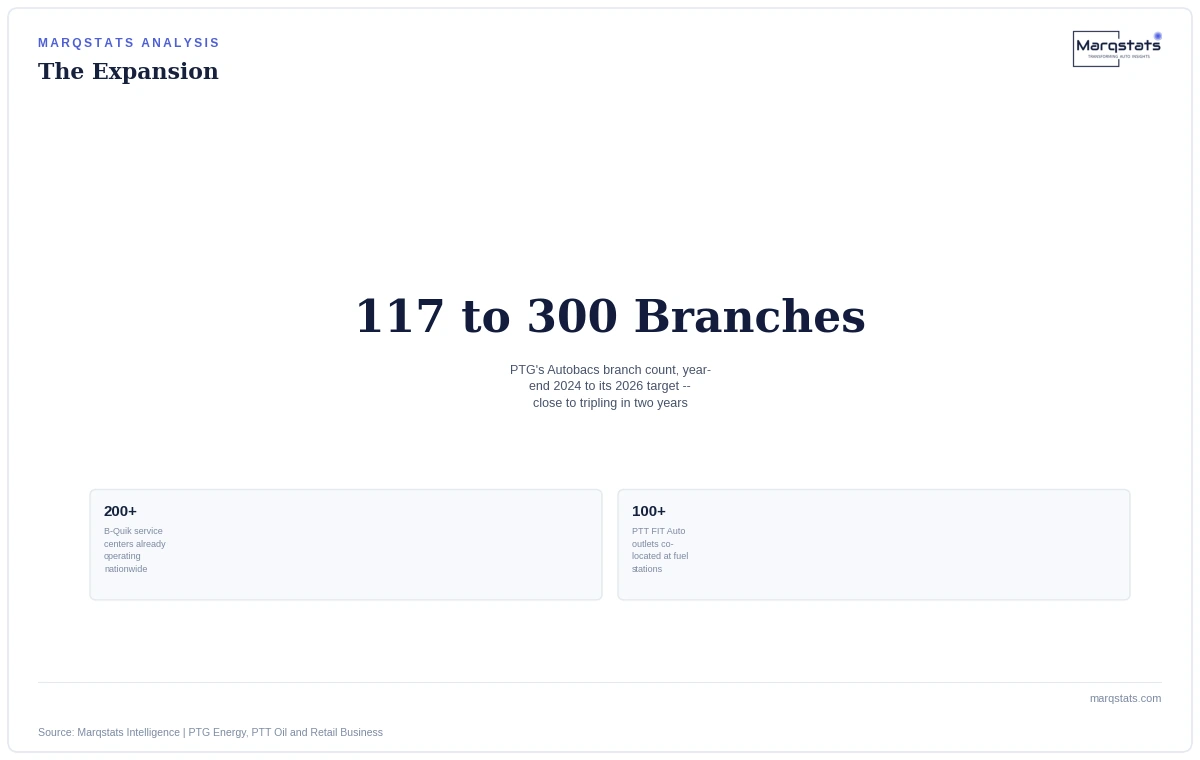
PTG Energy's Autobacs chain opened its 100th branch in October 2024, reached 117 by year-end, and is targeting 200 branches in 2025 and 300 by 2026, close to tripling its footprint in roughly two years. It isn't alone. B-Quik, Thailand's leading independent fast-fit operator, already runs more than 200 modern service centers built into hypermarket complexes and arterial road junctions. PTT Oil and Retail Business has pushed its own FIT Auto chain past 100 outlets, deliberately co-located inside PTT fuel stations to capture routine maintenance during a fuel stop.
What They're Actually Selling
None of these three chains is competing primarily on price. What they bundle into a single visit is the differentiator: a free 30-to-35-point safety inspection, transparent fixed pricing quoted before work begins, a digital vehicle service history the customer can pull up on a phone, and credit-card loyalty promotions that reward the next visit before this one is finished. An unaffiliated independent garage, however skilled the mechanic, has no easy way to replicate that bundle without the corporate backing, software, and marketing budget behind it.
Why an Independent Garage Can't Just Copy the Playbook
The gap isn't mechanical skill, it's infrastructure. Digital service-history tracking requires a software platform and ongoing IT support. Transparent fixed pricing requires standardized parts and labour costs across a network large enough to negotiate bulk rates. Credit-card loyalty promotions require a payments partnership at a scale no single shop can negotiate alone. A traditional independent garage, which the source data describes as serving vehicles over 7 years old with mineral oils and bulk drum supply, competes on price and personal trust with a regular customer, a real advantage, but a narrowing one as the fast-fit bundle keeps adding features an individual shop simply cannot match one at a time.
What This Means for Blenders and Distributors
The practical takeaway: as fast-fit chains scale, they concentrate purchasing power into a small number of national accounts that can dictate formulation, packaging and pricing terms in a way thousands of independent garages never could individually. Blenders and distributors should treat certified network partnerships with these chains, not broad-based independent-garage coverage, as the higher-leverage channel investment over the next two to three years, while still supporting the independent segment that continues to hold the largest single share of volume today.



